


Vehicle owners in India, when purchasing a four-wheeler insurance plan, come across the terms zero depreciation or bumper-to-bumper car insurance. Both terms are the same and offer protection against depreciation-related deductions during a four-wheeler insurance claim.
Understanding how this cover works during a claim can help you make informed decisions when purchasing a plan. Continue reading to explore in detail about the zero depreciation cover or bumper-to-bumper car insurance.
Are Bumper-to-Bumper Car Insurance and Zero Depreciation the Same?
Yes, zero depreciation and bumper-to-bumper car insurance are the same type of coverage. It is available as an add-on or rider under a comprehensive four-wheeler insurance plan offered by leading insurers like TATA AIG. Generally, when you file a car insurance claim, the insurance provider deducts the depreciation based on the vehicle age and the parts being replaced.
This means you have to pay a portion of repair expenses out of your pocket. However, with this add-on in place, you will receive a full claim payout without any depreciation deductions.
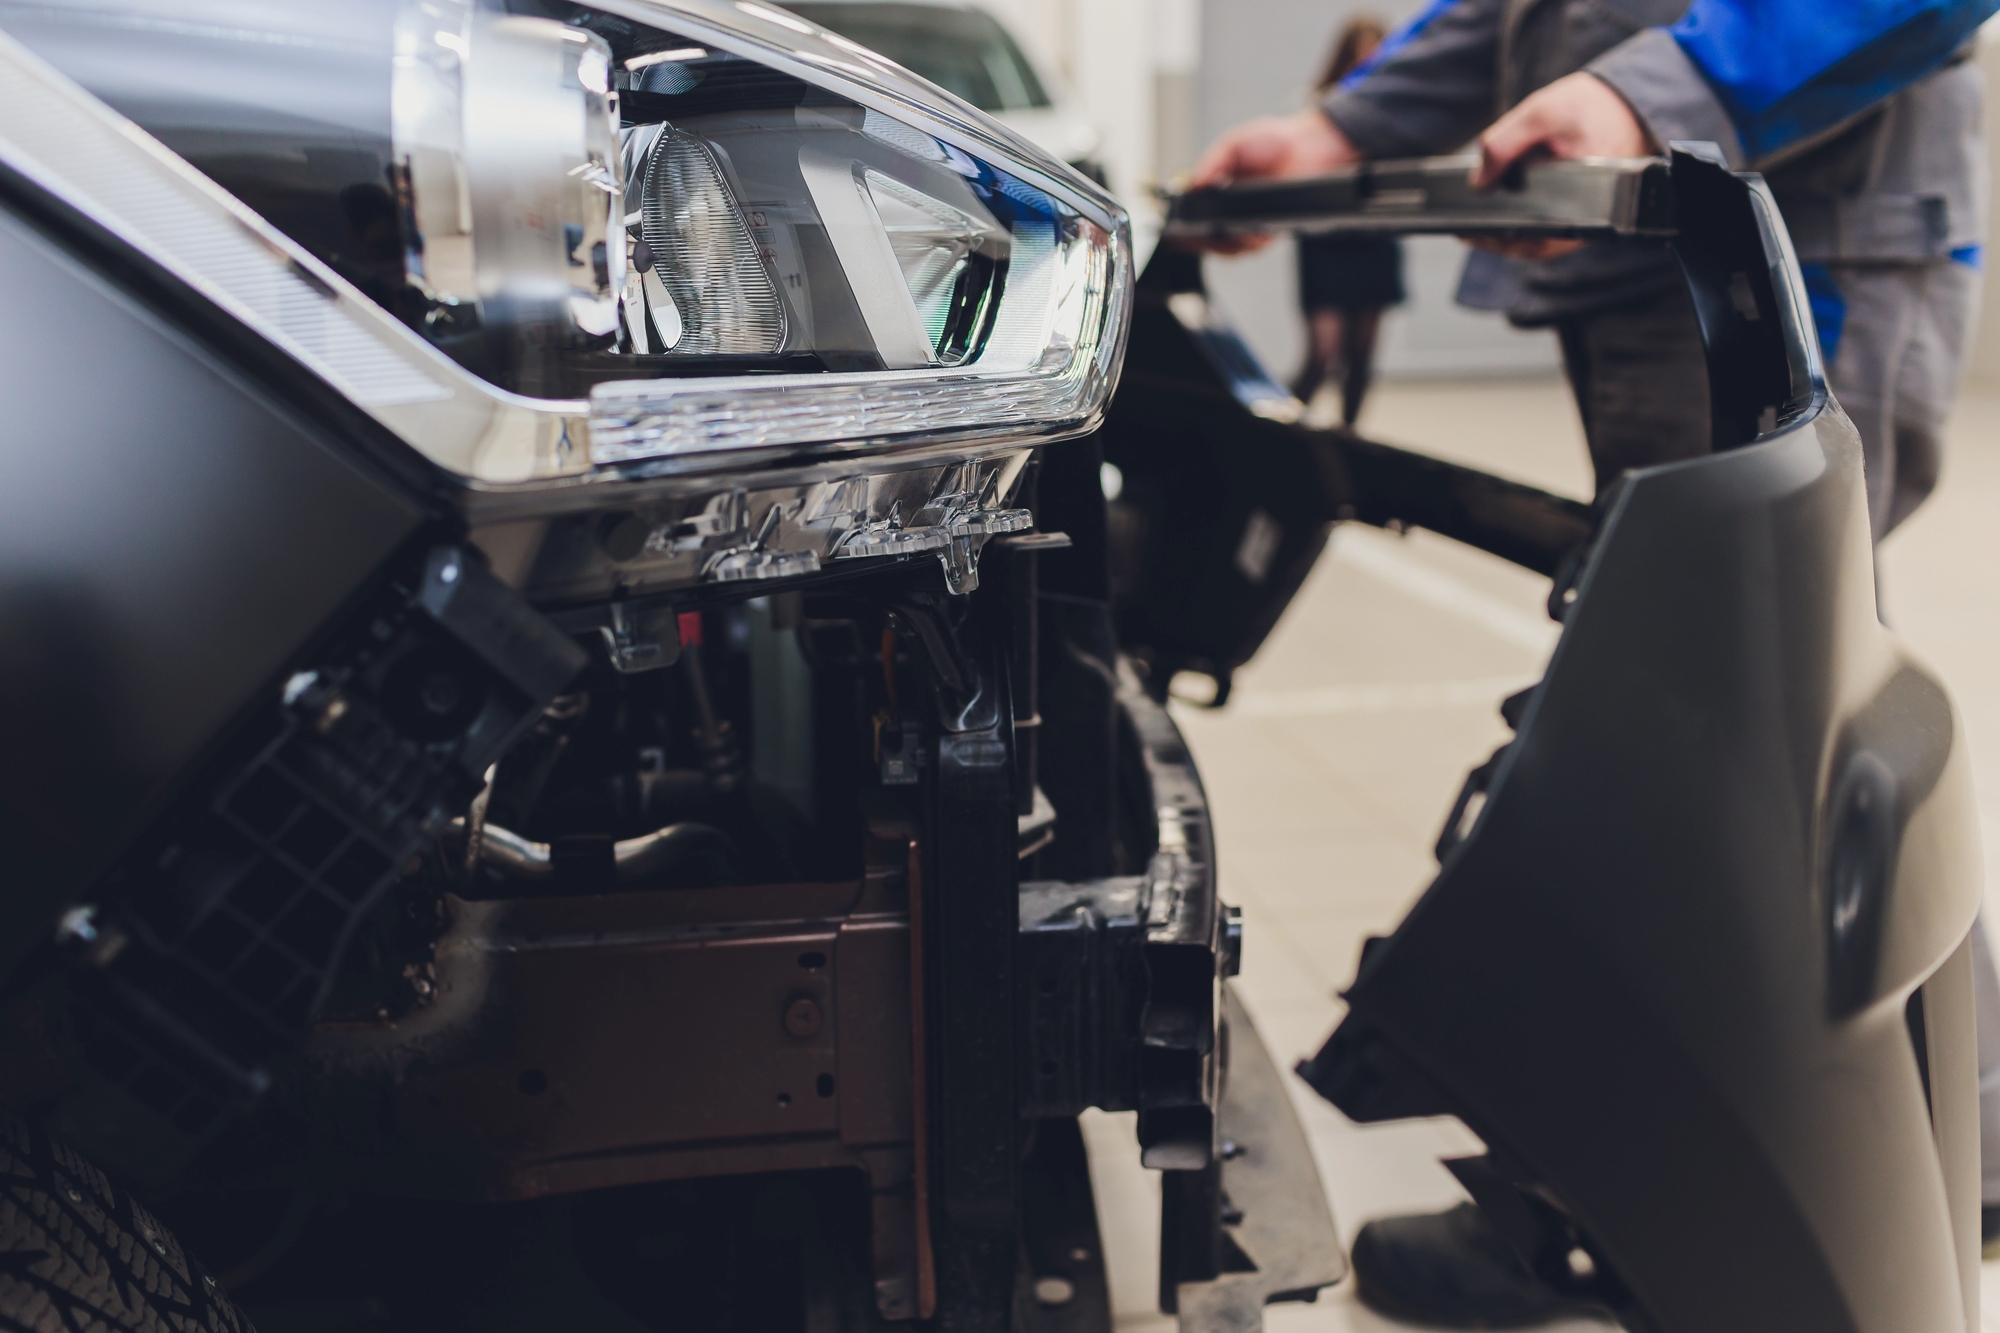
For example, suppose you damage your car’s bumper while driving, and the repair costs around ₹7000. With this add-on in place, you will receive the full repair expenses, i.e ₹7000 minus the deductible, if applicable.
What Does it Cover?
This cover pays the depreciation costs on eligible car parts after an insured accident. These may include plastic, rubber, fibre, and metal components, depending on the policy terms. By covering the depreciation deduction, the add-on can reduce your out-of-pocket repair expenses and help you receive a higher claim payout.
- Any damage and loss to the vehicle while driving under the influence of alcohol.
- Any claims arising when the driver does not have a valid driving licence.
- Any damage and loss to vehicles caused by mechanical or electrical breakdowns.
Who Would Benefit from Bumper-to-Bumper or Zero Depreciation Cover?
New Car Owners
New cars are often expensive to repair but their owners would want to maintain their vehicle in good condition. Zero depreciation cover can be useful because it reduces depreciation deductions on eligible parts after an insured accident.
So if you want to protect your vehicle against depreciation deductions, you can choose the comprehensive car insurance plan with a zero depreciation add-on, based on the age of the vehicle, usage and policy terms.