


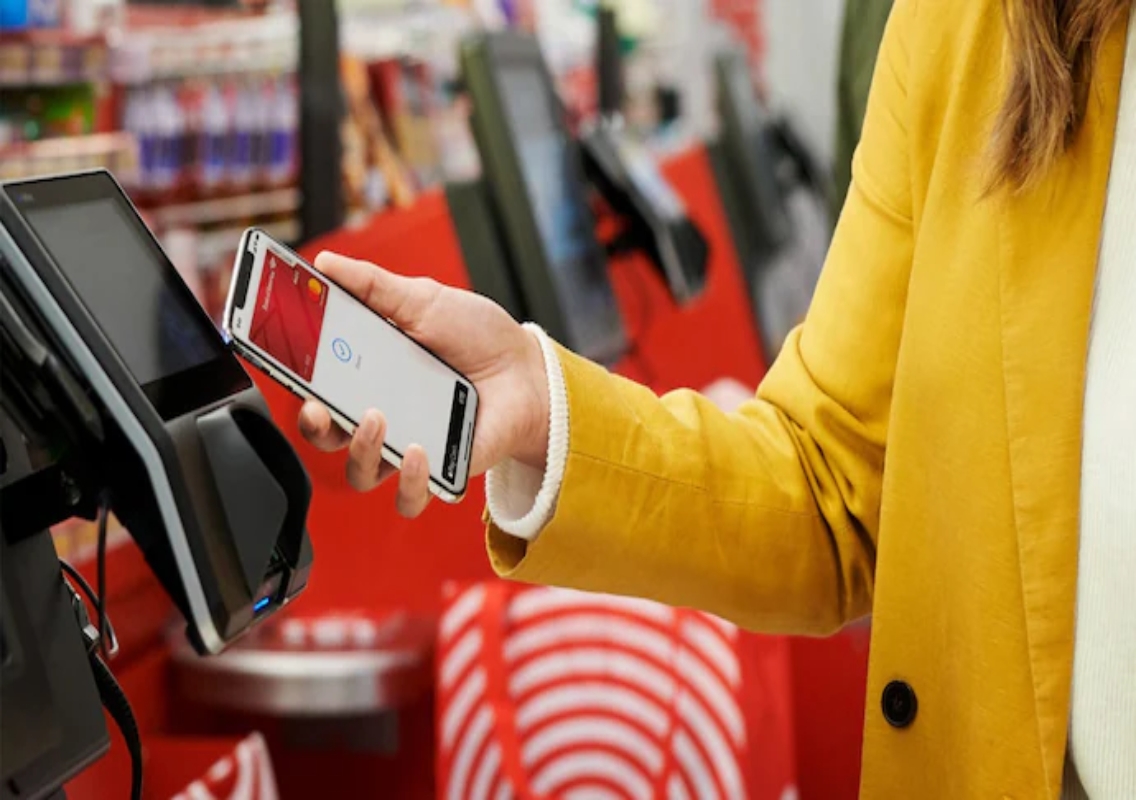
New Delhi: Apple Pay has finally arrived in India, more than a decade after Apple launched its payment service in the US. The service offers iPhone, iPad and Apple Watch users a convenient way to make card payments by simply authenticating on their device and tapping it against a compatible contactless payment terminal.
However, Apple Pay enters a market that is very different from many of the countries where it has already become an established payment option. India’s digital payments ecosystem is dominated by the Unified Payments Interface (UPI), which has made QR-code payments and instant bank transfers part of everyday transactions.
At launch, Apple Pay in India is also limited to Visa and Mastercard credit cards issued by Axis Bank. Apple is expected to add more banking partners, but the absence of UPI support means the service currently occupies a narrower space in India’s payments market.
How Apple Pay works in India
Apple Pay is designed around contactless card payments. Once an eligible card is added to Apple Wallet, users can authenticate a transaction using Face ID, Touch ID or the device passcode and hold their device near a contactless payment terminal.
Unlike conventional card payments that may require inserting or swiping a physical card, Apple Pay uses the device itself as the payment interface.
On supported iPhones, users can double-click the side button, authenticate themselves and hold the top of the phone near the contactless reader. Apple Watch users can similarly bring the watch close to the terminal.
The process does not require users to enter an OTP or manually type their card details at the checkout.
Apple also uses tokenisation for security. The actual card number is not stored on the device or Apple’s servers and is not shared directly with the merchant. Instead, Apple uses a unique Device Account Number stored securely in the device’s Secure Element.
The biggest limitation: no UPI at launch
The most important difference between Apple Pay in India and other payment services is its limited scope.
Apple Pay currently works as a card payment service, rather than as another UPI app.
That matters because UPI has become deeply embedded in India’s daily payment habits. Consumers routinely scan QR codes at shops, restaurants, street stalls and service establishments, while payments are directly linked to bank accounts.
Apple Pay does not currently support UPI transactions in India. Earlier reports had already indicated that Apple was taking a card-first approach for the Indian launch rather than immediately integrating UPI.
This means Apple Pay is unlikely to replace apps such as Google Pay or PhonePe for users whose primary requirement is everyday UPI payments.
Instead, Apple Pay is positioned more specifically around card-based contactless payments, particularly for consumers who already use credit cards and Apple devices.
India’s payment habits are different
Apple Pay’s convenience is evident in markets where contactless card payments are widely used. But India has developed a particularly strong QR-based payments culture.
UPI allows consumers to pay directly from their bank accounts without necessarily owning a credit card. This has helped digital payments reach small businesses and merchants across the country.
The service’s popularity also means Indian consumers may not necessarily view Apple Pay as a replacement for their existing payment applications.
Industry researchers cited by India Today have pointed out that UPI is likely to continue dominating everyday payments, while Apple Pay can occupy a different position based on convenience, privacy and the reduced friction associated with card payments.
The distinction could become particularly important at physical stores where compatible contactless terminals are available.
Axis Bank is the starting point
Apple Pay’s initial Indian rollout is deliberately limited.
Currently, users can add eligible Axis Bank Visa and Mastercard credit cards to Apple Wallet. Other banks and card networks are expected to be added over time.
Axis Bank’s position as a major credit-card issuer gives Apple Pay an initial customer base, but the number of participating banks will be an important factor in determining how widely the service is adopted.
Industry analysts cited by India Today said the pace at which additional banking partners join the platform will determine how much the potential user base expands.
For users of other banks, this means having an iPhone or Apple Watch alone is not enough to start using Apple Pay with their existing credit cards.
Contactless payments could give Apple Pay an opening
Despite the limitations, India has a growing ecosystem of contactless card payments.
Apple Pay can simplify the experience by replacing the physical card with an authenticated device. This could be particularly useful for consumers who already prefer credit cards for higher-value purchases, travel and payments at organised retail outlets.
Cashfree senior vice-president Nitin Pulyani told India Today that India’s annual credit-card transaction volume reached 5.7 billion transactions in 2025, up 2.6 times from 2021. He said Apple Pay could reduce friction associated with card payments.
Apple Pay could therefore complement rather than directly compete with UPI, at least in its current form.
Security and privacy are part of Apple’s pitch
Apple is also highlighting security and privacy as key features of Apple Pay.
Instead of sharing the actual card number with merchants, Apple uses a device-specific account number and transaction-specific security mechanisms. The transaction is authenticated on the user’s device.
Mastercard has also highlighted its tokenisation technology for Apple Pay transactions, which replaces sensitive card information with a secure token.
For consumers who are already comfortable with the Apple ecosystem, this creates a payment experience that does not require opening a separate app or repeatedly entering card details.
Apple Pay has room to expand
Apple’s Indian launch is only the beginning of its payments push in the country.
Globally, Apple Pay is available across more than 90 countries and works with thousands of banking and network partners. In India, Apple is expected to expand its banking partnerships over time.
The company may also eventually support debit cards in India, although the timing and exact scope of any such expansion remain uncertain. Whether UPI will eventually become part of Apple Pay in India is also not confirmed.
Apple Pay currently works on iPhones from the iPhone XR onwards, provided they run iOS 18 or later. It is also supported on Apple Watch Series 6 and later with compatible watchOS versions, while a Mac version is expected later.
Apple Pay’s India challenge is not just technology
The arrival of Apple Pay gives Indian consumers another digital payment option, but its success will depend on more than the quality of Apple’s technology.
The service has to fit into a market where consumers already have a fast, widely accepted and bank-linked payment system in UPI. At the same time, Apple needs to expand bank and merchant support if it wants Apple Pay to become a mainstream payment option rather than a niche convenience for selected cardholders.
For now, Apple Pay’s biggest strength in India is its simplicity: authenticate, tap and pay. Its biggest limitation is equally clear — it is entering a country where millions of people are already accustomed to opening a UPI app, scanning a QR code and completing a payment directly from their bank account.