


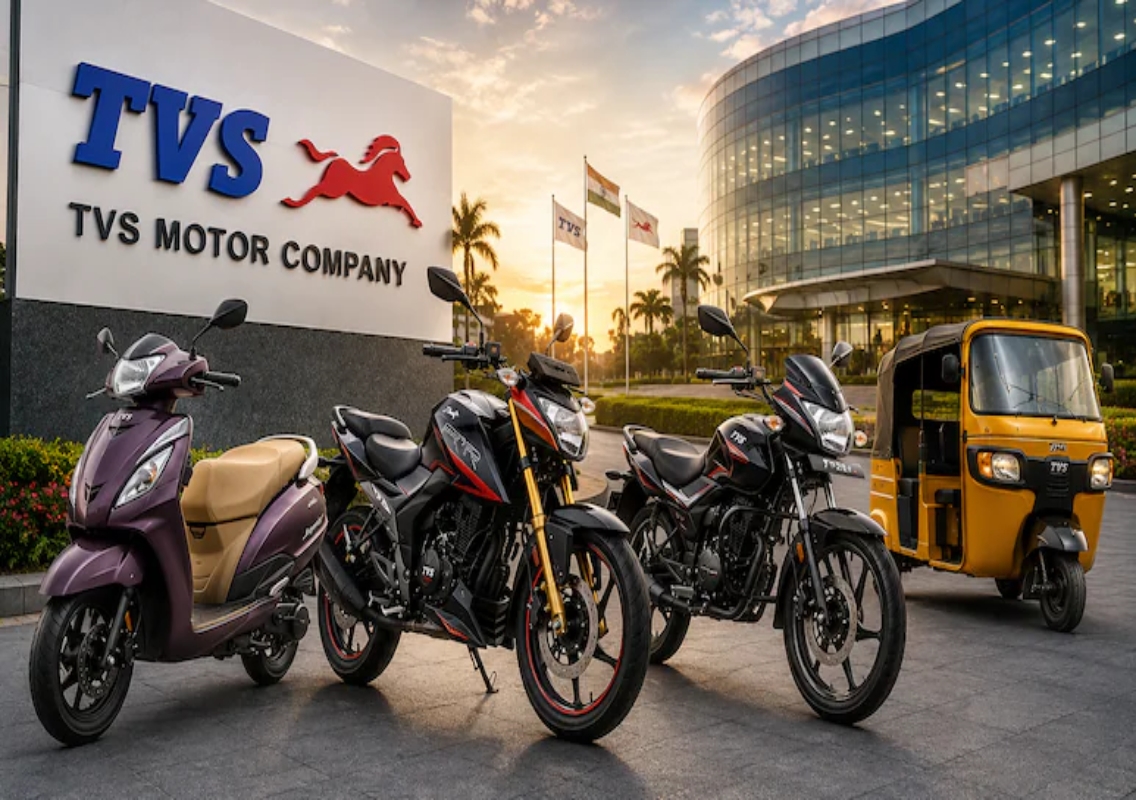
Chennai: TVS Motor Company’s record second-quarter performance has prompted several brokerages to raise their price targets, supported by strong vehicle sales, improving margins and growth in electric two-wheelers and exports. However, Citi has retained its ‘Sell’ rating on the stock, highlighting concerns over valuation despite increasing its target price.
The company reported a 47% year-on-year increase in earnings before interest, tax, depreciation and amortisation (EBITDA) to ₹2,219 crore for the July–September quarter of FY2026–27. Standalone net profit rose 52% to ₹1,377 crore, while revenue from operations increased 44% to ₹17,103 crore.
The results have strengthened the outlook among brokerages including Goldman Sachs, Jefferies, Macquarie, Kotak Neo and Emkay. Their assessments point to market-share gains, stronger operating performance and opportunities from the company’s expanding electric-vehicle business. Citi, meanwhile, remains cautious about how much future growth is already reflected in the share price.
Record sales support earnings growth
TVS Motor’s total two- and three-wheeler sales rose 27% year-on-year to approximately 19 lakh units during Q2 FY27. The broad-based increase in volumes helped the company deliver its highest-ever quarterly operating earnings.
Standalone revenue climbed to ₹17,103 crore from ₹11,905 crore in the corresponding quarter of the previous financial year. Net profit increased to ₹1,377 crore from ₹904 crore.
Operating EBITDA rose to ₹2,219 crore from ₹1,507 crore, while the EBITDA margin improved to 13% from 12.7%. The improvement came despite pressure from higher commodity costs.
Sales growth extended across several product categories. Motorcycle sales increased 28% to 8.58 lakh units, while scooter sales rose 29% to 8.25 lakh units. Moped sales grew 12% to 1.57 lakh units, and three-wheeler volumes increased 47% to 78,475 units.
International two- and three-wheeler sales rose 35% to approximately five lakh units. Electric two-wheeler sales more than doubled, increasing 133% to 1,86,186 units from 80,009 units a year earlier.
The figures indicate that TVS Motor’s growth is being supported by multiple segments rather than a single product category. Continued demand, however, will remain important as the company navigates higher input costs and changing market conditions.
Goldman Sachs raises target to ₹5,290
Goldman Sachs has maintained its ‘Buy’ rating on TVS Motor and raised its target price to ₹5,290 from ₹4,950.
The brokerage expects further market-share gains and margin improvement in the second half of FY27. It also sees the proposed demerger of TVS Motor’s consumer-finance business as a potential opportunity to unlock shareholder value.
The assessment reflects expectations that strong sales and improved operating performance could support earnings growth in the coming quarters. The potential value-unlocking effect of the finance-business restructuring provides another factor for investors to monitor.
These expectations remain dependent on the company sustaining demand and converting sales growth into profitability.
Jefferies highlights a 23-year market-share high
Jefferies has retained its ‘Buy’ rating and set a target price of ₹5,425.
The brokerage pointed to stronger sales volumes, improved profitability and continued export momentum. It also highlighted TVS Motor’s domestic two-wheeler market share reaching 20%, its highest level in 23 years.
Market-share gains can strengthen a manufacturer’s competitive position by improving its ability to attract customers across product categories. For TVS Motor, growth in scooters, premium motorcycles and electric vehicles will be important to sustaining this performance.
However, future market-share gains will depend on demand, new product launches, competition and the company’s ability to maintain attractive pricing.
Emkay raises target to ₹5,600
Emkay has retained its ‘Buy’ rating and raised its target price by approximately 6% to ₹5,600, the highest target among the six brokerages listed in the report.
The brokerage increased its earnings-per-share estimates for FY27, FY28 and FY29 by approximately 11%, 8% and 7%, respectively, largely reflecting stronger average selling prices.
At the same time, Emkay reduced its target valuation multiple to 33 times from 35 times. It cited the fading boost from post-GST-cut growth and rising macroeconomic risks, including fuel prices and interest rates.
Emkay expects healthy two-wheeler demand and single-digit growth in the internal combustion engine segment during the second half of FY27. It also expects electric-vehicle growth to remain strong.
The revised estimates therefore reflect both improved company-specific performance and a more cautious assessment of the broader economic environment.
Macquarie and Kotak Neo remain positive
Macquarie has maintained its ‘Outperform’ rating on TVS Motor with a target price of ₹4,325. Its assessment highlights EBITDA growth of 47%, the improvement in operating margin to 13%, the proposed consumer-finance demerger and capacity expansion.
Kotak Neo has retained its ‘Add’ rating and raised its target price to ₹4,400 from ₹4,350.
The brokerage expects TVS Motor to continue gaining market share in scooters, premium motorcycles and electric vehicles. The company’s ability to expand across these categories could help diversify its growth drivers.
The target prices and ratings differ because brokerages use different assumptions about earnings, valuation multiples and future growth. They should be treated as analyst estimates rather than guaranteed future share prices.
Citi retains ‘Sell’ despite raising target price
Citi has increased its target price for TVS Motor to ₹3,600 from ₹3,500 but retained its ‘Sell’ rating.
The brokerage acknowledged that higher realisations and production-linked incentive benefits helped offset rising operating costs. It also recognised the potential value-unlocking opportunity from the proposed demerger of the consumer-finance business.
Nevertheless, Citi remains concerned about the stock’s valuation. Its position contrasts with the more positive assessments from Goldman Sachs, Jefferies, Macquarie, Kotak Neo and Emkay.
The difference illustrates an important distinction in equity analysis: a company can report strong earnings growth while its shares may still be considered expensive relative to expected future profits.
Citi’s higher target price does not mean that the brokerage has become bullish. Its continued ‘Sell’ rating signals that it believes valuation risks remain significant under its assumptions.
What investors will watch next
TVS Motor’s next phase of growth will depend on whether it can maintain market-share gains, expand exports, grow electric-vehicle sales and protect margins from raw-material costs.
The proposed consumer-finance demerger is another development investors will monitor for its potential impact on business structure and shareholder value. The timing and eventual benefits of such a restructuring remain important considerations.
Demand in the second half of FY27 will also be closely watched, particularly as the comparison with the previous year becomes more challenging. Fuel prices, interest rates, commodity costs and competitive activity could influence both sales and profitability.
The brokerage assessments present two different perspectives on the stock. Most of the firms covered in the report remain positive on TVS Motor’s earnings momentum, while Citi’s continued ‘Sell’ call reflects concerns about valuation.
For investors, the distinction is between the company’s operating performance and the price paid for its shares. The strong quarterly results provide evidence of business growth, but analyst targets and ratings remain opinions based on assumptions that can change as new financial data emerges.